Land Subdivision Finance & Loans

What is land subdivision finance?

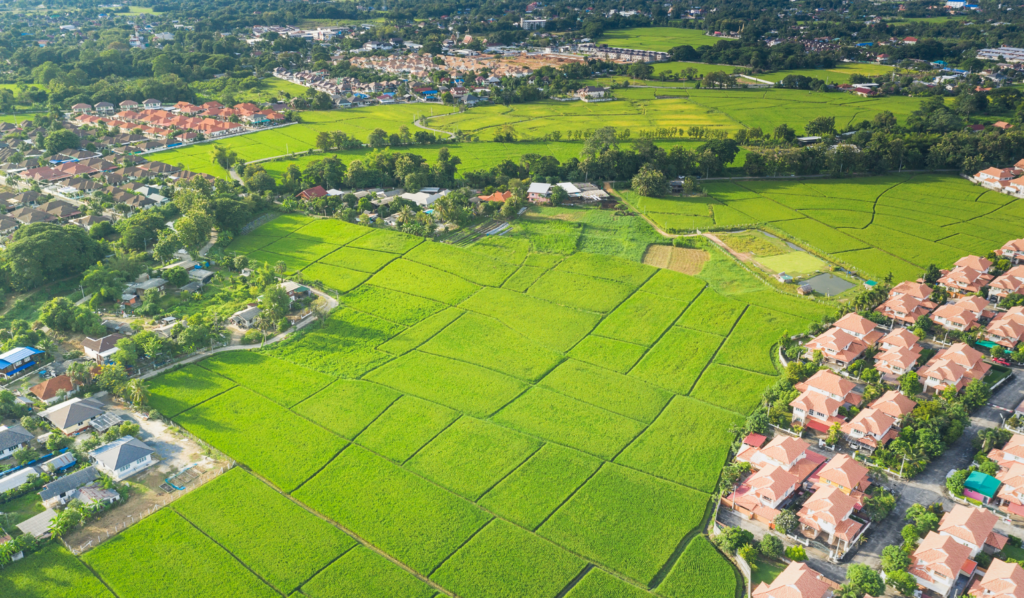
Land subdivision finance is a loan used to split one block into two or more lots and pay for the approvals and civil works needed to create new titles. Lenders usually fund the civil works in stages once a planning permit or development consent is approved, and the loan is repaid by selling the new lots or refinancing them. PostYourLoan compares subdivision loans across lenders for small residential subdivisions and larger projects, and manages the application for you.

Key points

  • Subdivision finance mostly funds the civil works, released in stages after approval.
  • Early costs (planning, surveys, permit) are usually paid from your own funds or equity.
  • Lenders look at approvals, feasibility, your contribution, the contractor’s quote and your exit plan.
  • The loan is repaid by selling lots or refinancing the lots you keep.

How subdivision loans work

Most subdivisions move through the same stages, and the finance follows them:

  1. Feasibility and planning approval: design, surveys and the permit application. These early costs are usually paid from your own funds or equity in another property.
  2. Plan certification and authority conditions: council and the water, power and telecommunications authorities set the works your lots need.
  3. Civil works: driveways or roads, drainage, sewer, water, power and telecommunications connections. This is where subdivision finance is mostly used, released in progress payments as the work is done.
  4. New titles: once council confirms the conditions are met, the plan is registered and separate titles are issued.
  5. Exit: the loan is repaid from lot sales, or the lots you keep are refinanced to standard home or investment loans.

On many subdivision facilities, interest can be added to the loan during the works instead of being paid monthly. Your lender will explain how its facility handles this.

Subdivision loan terms explained

TermWhat it meansWhat affects it
Loan termUsually short-term, matched to how long the project takesProject size, approval and works timeline
How funds are drawnProgress payments against completed works, often checked by a quantity surveyor or engineerBuilder’s contract and payment schedule
InterestPaid monthly, or capitalised (added to the loan) during worksLender policy and your cash flow
SecurityUsually the land being subdivided; sometimes another property as wellHow much of the cost you contribute
Loan amountBased on total project cost and expected value of the finished lotsYour contribution, feasibility, experience
ExitRepayment from sales, refinance or bothLot values, demand, presales for larger projects

Every lender sets its own limits, so we compare terms across lenders for your project rather than quoting a single figure.

Benefits of Land Subdivision Financing

Maximize Land
Value

Divide large plots of land into smaller, more valuable parcels to increase property value

Flexible Financing Options

Choose financing terms that suit your land subdivision project’s scope and timeline.

Increase Profit Potential

Subdividing land opens up the opportunity to sell individual plots or develop residential, commercial, or mixed-use properties.

Access to Development
Capital

Secure the capital needed to cover infrastructure costs, such as roads, utilities, and site preparation for each.

Types of subdivision we can help finance

Commercial Land Subdivision

Access residential subdivision finance to fund the subdivision of land for residential development, including single-family homes, duplexes, multi-unit dwellings, and townhouse projects.

Residential Land Subdivision

Finance the subdivision of land for residential development, including single-family homes, multi-unit dwellings, or townhouse projects.

Mixed-Use Development

Finance land subdivision for mixed-use developments, combining residential, commercial, and recreational spaces in a single project.

Infrastructure Financing

Access capital to fund infrastructure costs such as utilities, roads, drainage, and other essential services for your subdivision. Our subdivision loans are designed to cover these costs upfront, so infrastructure work never has to wait on cash flow.

This includes two- or three-lot residential (backyard) subdivisions, larger estates with new roads and services, Torrens title subdivisions creating separate lots, strata or owners corporation subdivisions such as townhouses sharing common property, and rural or lifestyle lot subdivisions.

Residential subdivision development loans

A two- or three-lot “backyard” subdivision is treated differently from a multi-lot estate. Small subdivisions are often funded by banks or non-bank lenders much like a construction loan, sometimes with your existing home as security. Larger projects with roads and many lots are usually funded as development finance, where lenders look closely at feasibility, experience and presales. For bigger projects, see our development loans.

What lenders assess

  • An approved planning permit or development consent, and the authorities’ conditions
  • A feasibility study showing total costs, expected lot values and a contingency
  • How much of the total cost you are contributing
  • Your civil contractor or builder and their quote
  • Your experience with similar projects
  • Your exit plan: sell, refinance or keep
  • Your income, assets and existing debts

Costs to budget for besides the loan

  • Town planner, land surveyor and engineering design
  • Council planning and certification fees
  • Water, sewer, power and telecommunications connection charges
  • Open space or development contributions, where your council or state requires them
  • Holding costs: interest, council rates and land tax during the project
  • Legal, registration and selling costs
  • Tax on sale (income tax and GST may apply; speak to a registered tax agent)
  • A contingency for cost overruns

Bank, non-bank or private lender for subdivision finance

Lender typeTypically suitsTrade-offs
Major banksSmall subdivisions with a strong borrower and a clear exitStricter policy; slower approvals
Non-bank lendersProjects outside bank policy, or borrowers with complex incomeOften higher cost; flexible structures
Private lendersShort-term or time-critical funding, second-ranking loansUsually the highest cost; short terms; exit must be clear

Need to fund early costs from equity? A second mortgage on another property is one option.

How we help with your subdivision finance

1

Initial Consultation

Our team assesses your land subdivision project and guides you through the land subdivision finance process, helping identify the most suitable financing options for your development goals.

1

Lender Comparison

We compare subdivision finance options from different lenders to find terms that suit your project.

2

Feasibility Assessment

We evaluate the feasibility of your land subdivision project, considering factors like zoning, infrastructure, and development potential.

3

Documentation and Application Assistance

We prepare the documents and application and deal with the lender through to approval.

Subdivision finance by location

After subdividing

Planning to build on your new lots? A construction loan can fund the homes. Holding land for future rezoning instead? See land banking.

Subdivision finance FAQs

Usually yes, but your existing lender needs to approve it, and it will typically require part of the loan to be repaid before releasing each new lot’s title. Talk to your lender early.

Usually not. Most lenders fund a subdivision once the permit or consent is approved, so early costs are normally paid from your own funds or equity.

It’s short-term finance, usually matched to the project timeline from works starting to titles being issued and lots sold or refinanced.

Subdivision finance funds creating new lots. A development loan usually funds building dwellings or a larger project on the land. Some projects use both.

Possibly. Depending on your circumstances, selling subdivided lots can trigger income tax or capital gains tax, and GST may apply if the activity is treated as a business or enterprise. Speak to a registered tax agent before you start.

It varies by lender and project. Lenders compare your contribution with the total project cost and the expected value of the finished lots, so stronger equity and a sound feasibility usually mean more options.

It depends on the state and the approval. In Victoria, a certified plan of subdivision lapses if it isn’t registered within five years of certification. Planning permits and development consents also have expiry dates set out in the approval itself, so check the conditions on yours.

For small residential subdivisions, presales often aren’t required. For larger projects, many lenders ask for a level of presales before funding, although some non-bank and private lenders consider projects with few or none, usually at a higher cost.

Talk to us about your subdivision and we’ll compare subdivision finance options across lenders for your project.